Seller resources · By Amoni Capital
Published
Selling a Fire-Damaged House in Dallas: Repair or Sell As-Is?
A house fire can leave you making decisions about insurance, repairs and your next home at the same time. If your Dallas-area property has fire, smoke or firefighting-related water damage, you may be wondering whether to rebuild first or sell the property in its current condition.
You do not need to choose a selling path before understanding the facts. Start with four separate questions: Is the property safe to enter? What damage has been documented? What does the insurance claim actually cover and require? What would each realistic selling path leave you with?
The right answer depends on your property, insurance policy, any lender and municipal requirements, and the written sale terms. This guide helps you organize that decision; it does not promise that any buyer will purchase a fire-damaged property.
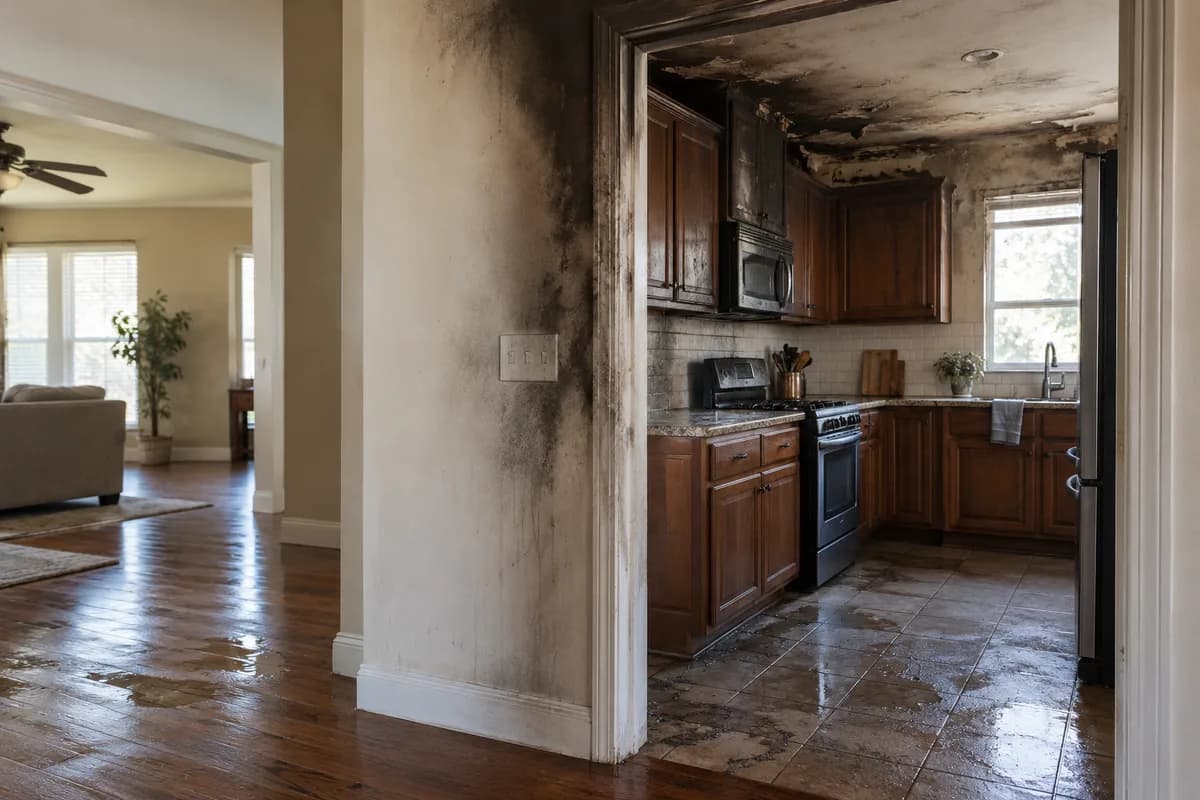
First: protect people and document the damage
Do not enter an unsafe structure or assume a home is safe because the fire has been extinguished. Follow emergency responders' instructions. If a professional assessment is needed, use appropriately qualified people rather than treating an online guide as a safety inspection.
Once it is safe, organize photographs or video of visible damage; communications with the insurer or adjuster; available fire-incident information; and invoices for emergency protective work. Record fire damage, smoke/soot damage and water damage from firefighting separately. A room that did not burn may still have damage that needs evaluation.
The Texas Department of Insurance advises homeowners to contact their insurer promptly, photograph damage, keep receipts, and generally make only necessary temporary protective repairs until the adjuster has inspected the loss. Check your policy and adjuster's instructions for your specific situation. TDI home insurance guide · TDI fire/smoke FAQ.
Separate the four files before deciding to sell
| File | Collect or confirm | Why it matters |
|---|---|---|
| Damage and safety | Photographs, known conditions, professional evaluations if obtained, emergency protective work | A buyer and contractor need an accurate picture; damaged areas should not be entered casually. |
| Insurance | Policy, claim number, adjuster’s estimate, any payment letters, deductible and any remaining claim questions | Insurance money is not the same as an accepted written purchase price. |
| Municipal/repair status | Any City notices, required permits, inspection or repair documentation | Repairing the physical condition does not by itself prove that any open municipal matter is closed. |
| Sale economics and terms | Repair bids if useful, carrying costs, mortgage payoff, realistic listing estimates, written direct-sale alternatives | Compare likely net proceeds and responsibilities, not just headline prices. |
On a small screen, scroll the table sideways to see every column.
This is an organizational framework, not a legal determination, damage estimate or guarantee that your property qualifies for a specific path.
Your insurance claim and your sale are two different decisions
Insurance coverage varies by policy. A homeowners policy may cover fire or smoke damage and additional living expenses in qualifying circumstances, but exclusions, limits, deductibles, depreciation, documentation and deadlines matter. Ask the insurer which parts of the loss are covered and what information it still needs. TDI home insurance guide.
Two issues deserve particular attention before signing a sale contract:
1. Is a payment tied to completing repairs?
Some replacement-cost policies pay an initial amount and release additional amounts after repairs or replacement. Selling rather than rebuilding may affect what can actually be collected under your policy. Ask your insurer for a written explanation; do not assume the estimate, approved claim, available check and cash you will retain are identical.
2. Does a mortgage company control part of the payment?
TDI says repair-claim checks on mortgaged homes are commonly made payable to the owner and mortgage company, and the lender may release funds as work is completed. Confirm payment, lien and payoff requirements with the lender and closing professional. TDI claims/payment guidance.
An open or disputed claim should not be described as automatically transferring to the buyer or automatically remaining with you after a sale. Whether the sale can proceed and who has rights to any insurance proceeds depend on the policy, claim status, lender rights, applicable law and precise written sale terms. Get qualified insurance, legal and title advice when the claim remains unresolved.
What if the house needs substantial rebuilding or permits?
A fire may damage far more than visible finishes. If you are considering repairs, ask a qualified professional for a scope suited to the actual loss. Confirm with the relevant municipality what permits or inspections may apply before beginning work.
For a property inside Dallas city limits, Dallas Planning and Development describes residential permits as approvals for construction, renovation and major repairs and directs applicants to the DallasNow portal. A house elsewhere in DFW follows that city's or other applicable jurisdiction's rules, not automatically Dallas's. Do not state that every fire repair requires the same permit or that any specific repair can proceed without one. City of Dallas residential permits.
If there is an active municipal notice or order, separately confirm its requirements and deadlines. Our Dallas code-violations guide explains why a physical fix, an open City record and a recorded lien are different matters.
Three ways to approach the sale
| Path | What you gain | What to examine before deciding |
|---|---|---|
| Repair, then list | Opportunity to market a documented restored property to a wider set of buyers | Uninsured costs, permits, contractor scope, lender/claim conditions, extra ownership time and uncertainty about eventual sale price |
| List in current condition | Market exposure without first finishing all restoration work | Buyer expectations, safety/access, inspections, disclosure duties, financing differences and realistic net proceeds |
| Compare a direct as-is sale | A written alternative that may reduce preparation and public-showing work if a suitable buyer exists | Actual buyer eligibility, repair-risk discount, proof of funds, insurance-claim treatment, title and closing responsibilities, and contract conditions |
On a small screen, scroll the table sideways to compare every column.
A direct sale is not automatically quicker, financially better or legally simpler. A listing is not automatically impossible because the property has fire damage. Compare actual property facts and complete written terms before choosing. Amoni's cash-offer vs. listing guide can help organize broader channel differences.
Option 1: Repair, then list
This can be worth considering if you have a clear professional repair scope, understand the insurance payment stages, can fund your share of the work and have a realistic reason to expect the completed home to produce better proceeds.
Get repair bids when they will meaningfully inform the decision. Keep emergency repairs separate from permanent restoration, confirm necessary permits and retain inspection or completion records where applicable. TDI also advises consumers to compare contractor bids, check references and beware of deductible-waiver offers. TDI fire claim and contractor tips. Amoni's major-repairs guide can help compare the broader repair tradeoffs.
Option 2: List in current condition
You can explore marketing the house as-is, but the actual property condition, buyer's intended use, access and financing need to be evaluated. Do not assume every financed buyer must refuse the property or that listing guarantees a better result.
As-is is not the same as undisclosed. The current TREC Seller's Disclosure Notice, Form 55-1 (effective May 28, 2026), includes questions about known defects and previous fires for transactions where that disclosure form applies. Eligibility and statutory exceptions vary, so use the correct form and transaction-specific professional guidance. Record known fire, smoke, water or other issues accurately rather than assuming repaired damage is irrelevant. TREC form page · Form 55-1. Amoni's selling as-is guide explains the broader channel.
Option 3: Compare a direct sale before committing to repairs
A direct buyer may be willing to evaluate the house in its current condition. That does not guarantee that Amoni Capital or another buyer will purchase it, accept unresolved insurance issues or waive inspections, title requirements or closing conditions. A written agreement controls any actual transaction. Amoni Terms.
Use a direct-sale proposal as one comparison point, alongside a realistic listing estimate or repair-first plan, rather than the only option. Ask how any claim, mortgage payoff, City notice, debris, access and other obligations are treated in the written agreement.
Compare how much money you may keep
Use your own quotes and written estimates, not online averages. Keep insurance assumptions separate until your insurer explains what you may actually receive if you sell rather than rebuild.
Enter your numbers
Choose an option, then enter your numbers. Switch options to compare. Your entries are not submitted.
Repair, then sell
Mortgage, taxes, utilities and upkeep
Only enter an amount your insurer has confirmed for this choice
Estimated amount you keep
$0
How the total works: the calculator starts with the sale price, subtracts only the costs shown for that option, then subtracts loans and liens and adds only insurance money your insurer confirms you can keep for that choice. This is an estimate—not a home value, insurance decision or tax calculation. Do not count the same money twice. Ask a title, insurance or financial professional for help when the claim or payoff is complicated. Amoni's Home Sale Calculator can help with other home-sale costs, but it cannot decide what insurance money you may receive.
What to do next
- 1
Stay safe. Secure the home and contact your insurer.
- 2
Ask what insurance covers, when it pays and if your mortgage company is involved.
- 3
Check the City’s permit and repair rules.
- 4
Get the estimates you need.
- 5
Compare at least two selling options using the same costs and timeline.
- 6
Read the full sale offer. Check the damage, insurance, loan, City issues and access terms.
- 7
Ask a qualified professional for help before signing if you still have questions.
Free DFW Home Sale Options Review
Want a second selling option before you rebuild?
Amoni Capital offers a free review to help homeowners organize the difference between selling directly as-is, listing as-is and repairing before listing. You can explain the known damage and your situation; the review is no charge, no obligation, not an appraisal, not an insurance or contractor estimate and not an automatic offer. Not every property qualifies for a direct offer.
Start a Free Home Sale Options ReviewIf the numbers are not yet clear, the best next step may be gathering your insurer's written response, documenting damage or getting a qualified repair opinion—not accepting any particular offer.
Frequently asked questions
Can I sell a fire-damaged house in Dallas without rebuilding it first?
You can explore a current-condition listing or direct-sale evaluation, but feasibility depends on the property’s safety and condition, buyers, any City requirements, title and the actual written terms. Do not assume every buyer will accept a fire-damaged property.
Should I finish my insurance claim before selling?
There is no universal answer. Before committing, ask your insurer and lender to explain claim status, payment stages, deadlines, the effect of selling rather than rebuilding and any unresolved rights. An open claim does not by itself establish who receives later funds.
Does an as-is sale eliminate fire-damage disclosure?
No. As-is terms do not eliminate disclosure obligations that apply to the transaction. TREC’s current Form 55-1 includes previous fires and known-defect questions; applicability and exemptions vary. Use the correct documents and professional guidance.
Do I need a Dallas permit to repair the damage?
It depends on the property and scope. For homes within Dallas city limits, check Dallas residential permitting and inspection guidance before undertaking major work. Elsewhere in DFW, contact the applicable jurisdiction.
Will Amoni purchase a home with severe fire damage?
Amoni may review the property information, but an evaluation does not guarantee an offer or purchase. Eligibility and any signed agreement control. Amoni does not determine your insurance rights.