Quick answer
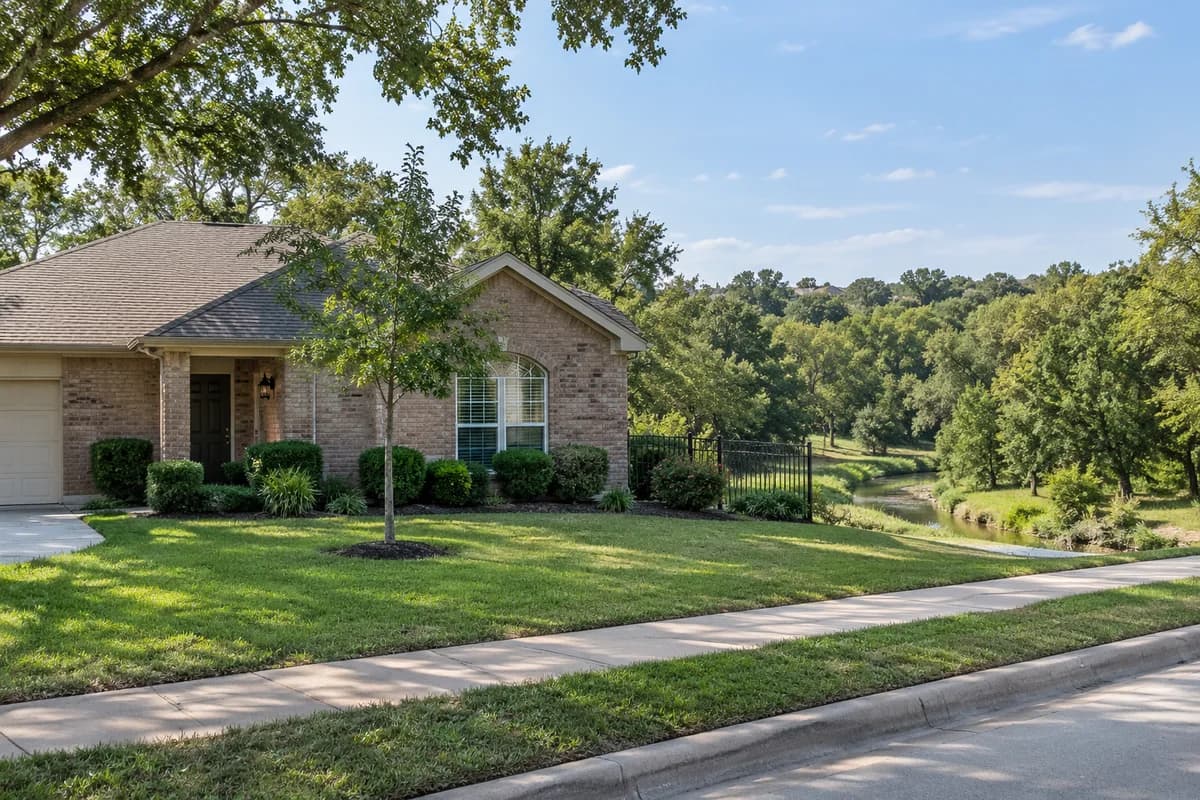
You can consider buying a house in a mapped Dallas floodplain, but first verify the exact address on current official maps, ask about past flooding and drainage, get a property-specific flood insurance quote, and check lender and renovation requirements. Being outside a high-risk mapped zone does not mean the house cannot flood.
Geography: Dallas city guidance with DFW jurisdiction caveats · Sources reviewed: October 8, 2026
1. Check the exact property on an official map
Start with FEMA's Flood Map Service Center. Enter the actual property address and review the current effective map and any applicable map-change documents; avoid relying solely on a screenshot from a listing or a map of the whole ZIP code.
For a property inside the City of Dallas, the City's Floodplain and Drainage Management program also directs owners and buyers to the DCAD map with the FEMA National Flood Hazard Layer, Dallas Zoning GIS and FEMA data. These layers can help identify where a property lies relative to regulatory floodplain boundaries. City of Dallas guidance.
What does the 100-year floodplain mean?
A 1% annual-chance floodplain represents an area with a modeled 1% chance of a qualifying flood event in any given year. It does not mean a flood happens on a fixed 100-year schedule. Maps describe modeled hazard boundaries, not a guarantee of what will or will not happen to a particular house.
2. Separate a FEMA flood zone from flood history
A property can have experienced drainage problems or flooding even when a current map does not place its building inside a Special Flood Hazard Area.
Ask for facts about the specific structure and lot:
- available seller disclosure and any known past flood or water entry;
- inspection findings for water intrusion or drainage;
- roof and ground-surface grading and visible drainage conditions;
- prior repairs and invoices where available;
- information on past flood insurance coverage or claims, if provided.
For covered transactions, Texas uses TREC's current Seller's Disclosure Notice (Form 55-1, effective May 28, 2026). Read the actual disclosure rather than treating a verbal statement as a substitute. TREC form.
3. Verify insurance requirements and price before relying on a budget
Is flood insurance required when buying in Dallas? It can be required for a mortgaged property in a designated Special Flood Hazard Area, depending on the loan and determination. CFPB says buyers should check the flood insurance requirement early and obtain their own quote. A seller's premium may not match what a new buyer will pay. CFPB guidance.
Most ordinary homeowners policies do not cover flooding from rising water. For a particular property, compare actual options with a licensed insurance agent rather than using a generic Dallas premium. Flood coverage has separate terms, limits, exclusions and possible waiting periods. The City of Dallas encourages owners to investigate coverage even outside the highest-risk mapped areas.
| Check | Evidence to request | Why it helps |
|---|---|---|
| Flood-map location | Effective FEMA map; City layer | Establishes mapped context for this address. |
| Seller's flooding history | Disclosure and available records | Shows what the owner knows, not a guarantee of condition. |
| Lender requirement | Written lender flood determination/request | Establishes transaction-specific insurance requirement. |
| Insurance cost | Quote for you at this address | Avoids using the seller's old premium as your budget. |
| Planned additions/renovation | City floodplain/permit guidance | Shows which project approvals may need review. |
Browser-only checklist
Flood Risk Buyer Checklist
Record where your due diligence stands. Nothing is submitted, stored or used to classify the property.
Your remaining checks
Choose answers above. The checklist will show only unresolved due-diligence actions.
FEMA Map Service Center · City of Dallas floodplain guidance
4. Check improvement restrictions before assuming you can renovate
If you plan to add a room, regrade a yard, rebuild or materially renovate a property in the City of Dallas regulatory floodplain, the City's floodplain office may need to review the project and permits. The City describes floodplain fill or alteration permits and review requirements for regulated development. Not every project follows the same rule; obtain parcel-specific confirmation before estimating cost or scheduling work.
A seller's statement that there is room for a pool or extension does not guarantee floodplain approvals.
5. Make sure you are using the correct jurisdiction
A Dallas mailing address may not tell you which governmental floodplain rules apply. Dallas County notes that its county floodplain office regulates unincorporated areas, while municipalities handle their own jurisdictions. If the property is in Fort Worth, Plano, Frisco, Garland, Irving or another DFW city, use that city's floodplain administrator rather than the City of Dallas program. Dallas County guidance.
6. Keep total housing cost and risk separate
Your buying decision should consider the purchase terms, mortgage payment, ordinary homeowners insurance, any flood policy, maintenance, and your reserve for emergencies. The Amoni Mortgage Calculator can help with basic payment inputs, but it is not an insurer or lender quote.
If a potential fixer-upper lies in a regulated floodplain, use the Fixer-Upper guide to organize contractor bids and financing questions without assuming permits will be approved. The Cash-to-Close guide helps keep insurance and escrow inputs visible.
7. A simple Dallas buyer process
- Check FEMA's current effective map for the exact property.
- Compare municipal layers and contact the floodplain administrator if uncertain.
- Read the seller disclosure and inspect for water and drainage concerns.
- Obtain a buyer-specific flood insurance quote and lender requirements.
- Confirm city approval rules if renovations or earthwork are planned.
- Build the actual payment and insurance budget and review contract deadlines.
FAQs
Can I buy a Dallas house in a high-risk FEMA flood zone?
Possibly, subject to your financing, insurance availability and requirements, contract, and risk tolerance. The zone alone does not decide for you.
Does Zone X mean no flood risk?
No. It is a mapped flood-hazard category, not a guarantee that flood damage cannot occur.
Can I use the seller's flood insurance bill?
Use it only as context. CFPB warns that a new buyer's premium can differ from the current owner's cost.
Will a conventional home policy cover river or street flooding?
Ordinary home policies generally exclude flood losses. Ask your insurer about a separate flood policy and the exact definitions.
Does buying in a floodplain prevent renovations?
Not automatically. But projects within a regulated floodplain may require special municipal review or permits; verify the address and scope with the city.
Want to compare DFW buying opportunities?
Amoni Capital makes eligible properties available to buyers and investors. View available opportunities or join the buyers list.